
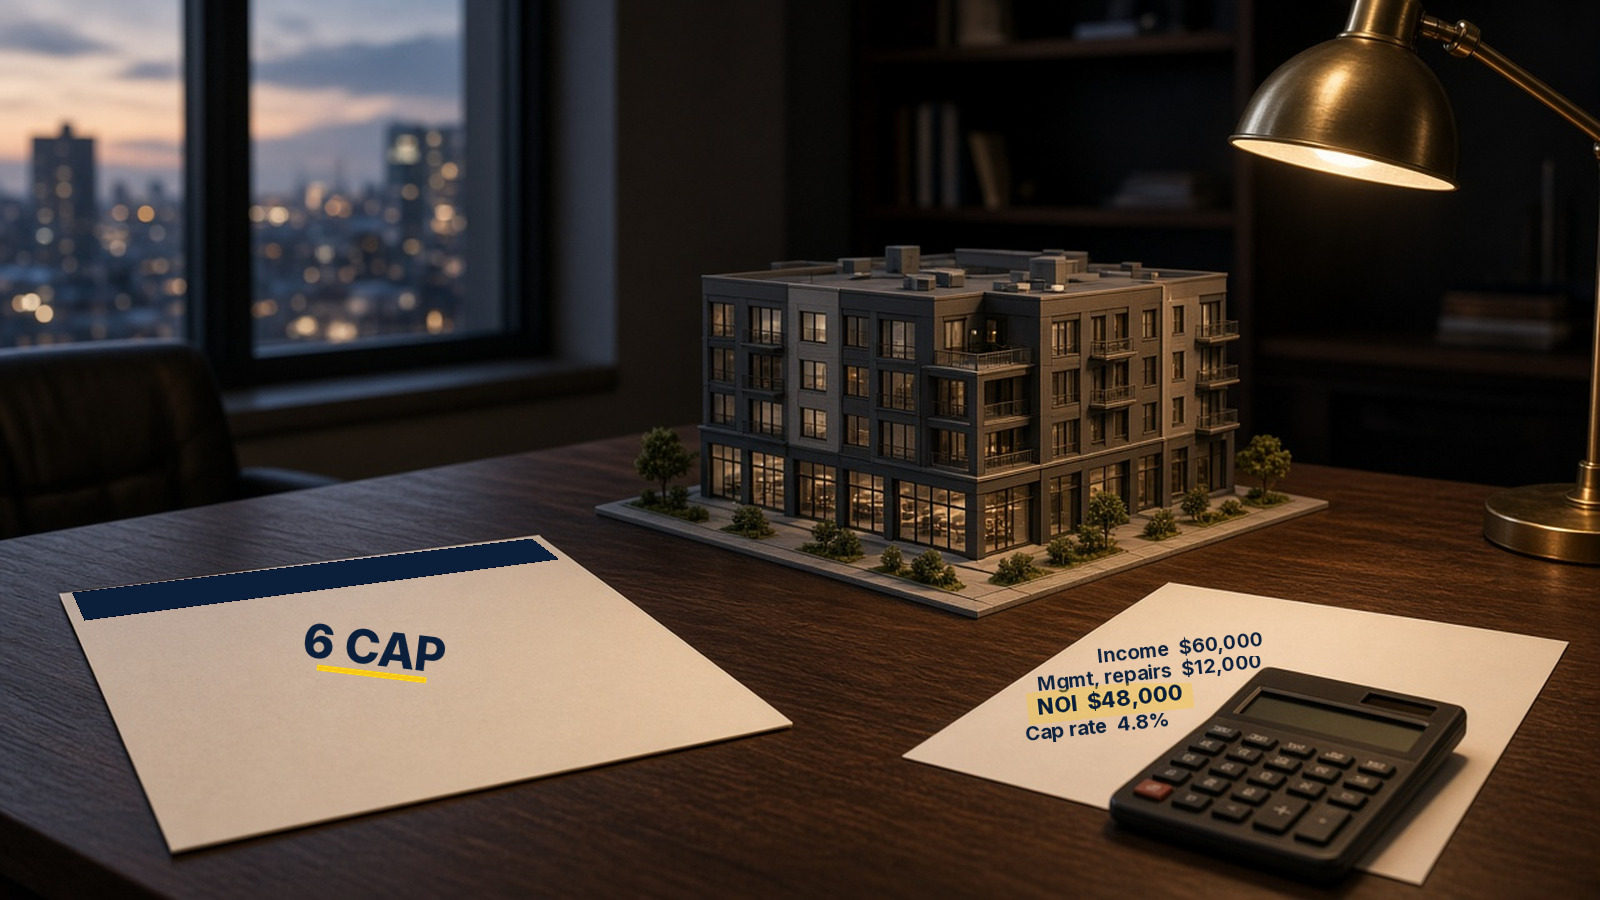
A broker sends you a flyer for a building listed at $1 million and calls it a six cap, which means the seller is telling you the building makes about $60,000 a year after expenses. If you buy at that price, every dollar of your offer rests on that $60,000 being real once you own the building. Before you sign anything, you have to answer whether that income still shows up after the seller hands you the keys.
Prefer to watch? Watch the full video on YouTube.
What a 6 cap is supposed to mean
Cap rate, short for capitalization rate, is the building's yearly net operating income divided by the price. Net operating income, or NOI, is the rent and other income after vacancy and operating expenses, before the mortgage and income taxes. $60,000 divided by $1 million is 6%, which is where the six cap comes from.
If you want the full formulas, our cap rate guide walks through the calculation and its limits, and our NOI guide shows what belongs in operating income and what stays out.
What happens when the seller's expenses aren't yours
Imagine the seller manages the building personally and does the repairs himself, so neither cost shows up on the expense sheet. Once you own the building, you'll probably pay someone for both, and taxes and insurance may also change after the sale.
Here is a hypothetical example, not a market average. Suppose paying for management and repairs adds $12,000 a year. Your NOI drops from $60,000 to $48,000. At the same $1 million price, the building you'd actually own is a 4.8 cap, not a six cap. To get back to a 6% cap rate on that $48,000 of NOI, the price would need to be $800,000, which is $48,000 divided by 0.06.
The seller's $60,000 only survives a change of owner if it still holds up after you add the costs you'll actually pay.
A higher cap rate can mean a lower price or higher risk
This can make you want to hunt for the highest cap rate you can find. A higher cap rate can mean a lower price for the same income. The market may also be pricing in a weak location, unreliable tenants, or expensive repairs. A lower cap rate may reflect confidence in a stronger location and more dependable rent. Neither percentage proves the seller's numbers are right, and neither one works as a complete risk score.
Start with the rent roll, not the flyer
I start with the rent roll, which is the list of every tenant, their rent, and their lease dates, along with the actual collections, because those records tell me more than the flyer. Then I ask what happens when a lease expires, a tenant leaves, or a major repair comes due.
Our rent roll guide shows how to read and verify that list, and the deal that looks great on paper is a reminder that a tidy NOI on a flyer can hide costs that show up after closing.
Put the mortgage in a separate calculation
The mortgage belongs in a separate calculation. Cap rate leaves debt out, but your cash flow after paying the lender depends on the loan amount, the interest rate, and the repayment schedule. A property can have positive operating income and still leave too little after the mortgage and reserves.
Rebuild the annual operating income with costs you can defend. Get an actual loan quote, or ask whether the seller would carry part of the price at a lower rate than the bank. Then subtract the debt payments and leave room for repairs and vacancy. The work may tell you to lower the offer or change the terms.
The cash-on-cash return guide helps you compare what's left after the loan with the cash you put in. If a seller carrying part of the price is on the table, how to run owner-financing numbers walks through the payment math, and the 100% seller-financing checklist covers due-on-sale and balloon risk.
Take the flyer and rebuild it like you were going to buy the building:
- Add management, repairs, taxes, insurance, and vacancy you can defend, and recalculate NOI.
- Divide that NOI by the asking price to get the cap rate you'd actually own, and divide the rebuilt NOI by the advertised cap rate to see the price that would restore it.
- Verify the rent roll against actual collections and lease dates, and ask what happens when a lease expires or a tenant leaves.
- Get a loan quote or seller-carry terms, then look at cash flow after debt service and reserves.
- Offer a lower price or different terms if the rebuilt numbers don't support the flyer.
The recap
- A 6 cap on a $1 million building means the seller is claiming about $60,000 of yearly NOI.
- Cap rate is annual NOI divided by price, and NOI is income after vacancy and operating expenses, before the mortgage.
- In a hypothetical example, adding $12,000 a year for management and repairs drops NOI to $48,000, which is a 4.8 cap at $1 million, or a $800,000 price if you want to stay at a 6 cap.
- A higher cap rate can mean a lower price or higher risk, and neither figure proves the seller's numbers.
- Start with the rent roll and actual collections, rebuild expenses you will pay, and keep the mortgage in a separate cash-flow calculation.
The $1 million price, the $60,000 NOI, and the $12,000 of added management and repairs in this guide are a hypothetical teaching example, not a market average or a promise of results. Verify rents, expenses, taxes, insurance, and loan terms on the actual property.
Rebuild the seller's numbers with us before you offer
Some sellers will say no, but if you never send the offer, you'll never find the deal that works. If you want to learn how to underwrite a property before putting your money into the deal, come join us in Commercial Real Estate 101 on Skool. Inside, we teach you how to rebuild a seller's numbers and structure offers, including seller financing, that you can hold.
Get the rent roll, rebuild the income, and make an offer the rebuilt numbers can support.
Frequently asked questions
What does a 6 cap mean on a $1 million building?
A 6 cap on a $1 million building means the seller is claiming about $60,000 a year of net operating income. Cap rate is yearly NOI divided by price, and $60,000 divided by $1 million is 6%.
How do you calculate cap rate on a property?
Cap rate is the building's yearly net operating income divided by the price. Net operating income, or NOI, is the rent and other income after vacancy and operating expenses, before the mortgage and income taxes.
Why can an advertised cap rate be wrong?
An advertised cap rate can be wrong because the seller's expense sheet may leave out costs you'll pay, like management and repairs the seller does himself, and taxes and insurance may change after the sale. In a hypothetical example, adding $12,000 a year for management and repairs drops NOI from $60,000 to $48,000, which makes the $1 million building a 4.8 cap.
Is a higher cap rate always better?
A higher cap rate isn't always better. A higher cap rate can mean a lower price for the same income, but the market may also be pricing in a weak location, unreliable tenants, or expensive repairs, and neither percentage proves the seller's numbers are right.
Does cap rate include the mortgage payment?
Cap rate leaves the mortgage out, so you run cash flow after the loan payment as a separate calculation. A property can have positive operating income and still leave too little after the mortgage and reserves.